

In Shandong, a province in eastern China, a woman in her fifties, a stay-at-home mother, films herself six hours a day folding laundry, pouring water, opening drawers. Gao Bo earns about twenty yuan an hour, roughly three dollars, to produce the gesture data used to train humanoid robots. JD.com, one of China’s e-commerce giants, says it wants to enlist up to 500,000 people like her; US firms outsource the same collection abroad. Alan Fern, a robotics researcher at Oregon State University, calls the method “very unproven.” The race does not stop for so little.
Gao Bo’s body is a raw material. What she makes will not go to a factory: the humanoids she trains are meant for spaces built for humans, a home, a shop, a cluttered warehouse, where a supple gesture is needed rather than a fixed line. That is already a clue. Taking the human out of work does not everywhere follow the same path, and confusing those paths distorts the reasoning. There are at least three. Public debate treats two as one and overlooks the third.
The factory built for human bodies admits only the human-shaped robot
An existing factory was drawn around the worker: bench height, bin size, tool grip, aisle width, everything is set to a body. To automate it without rebuilding, a machine shaped like the one it replaces is slipped in. The humanoid form has no other reason to exist: it fits a human environment no one wants to redo.
This is the regime documented by BMW’s pilot in Spartanburg, South Carolina. The Figure 02 robot loaded more than 90,000 sheet-metal parts there over 1,250 hours, with a placement rate above 99% and a steady cycle time, contributing to the production of more than 30,000 X3s. In May, then June 2026, BMW moved to the commercial deployment of the next model, Figure 03: a fleet of about 40 units on body and assembly stations, billed at around $25 per robot-hour, which Figure presents as the first paying humanoid contract at industrial scale, with extensions announced to the German sites of Munich, Regensburg and Leipzig. Hyundai follows the same road, further still: more than 25,000 Atlas robots planned across its plants, parts sequencing from 2028, full assembly targeted for 2030, with the stated aim of a line running lights-out.
This is the only one of the three regimes where comparing the worker’s gesture with the robot’s makes sense, because a human station stands opposite the automated one. A parity can therefore be figured, provided it is not overstated. A Western unit costs $90,000 to $100,000 today, according to Bank of America; its Chinese bill of materials comes closer to 35,000, and BofA projects it below $17,000 by 2030, a fall of about 13% a year. Goldman Sachs had measured a 40% drop in manufacturing costs between 2023 and 2024, a one-off not to be mistaken for a recurring rate. Per hour, the Spartanburg contract, about $25 per robot-hour, puts the robot below the cost of a US autoworker, paid $50 to $70, or of a German manufacturing worker, at about €49.50 an hour in the first quarter of 2026.
This comparison flatters the robot. It assumes the robot does a worker’s full job, which it is still far from. 2026 humanoids handle 60 to 80% of tasks in structured settings, but only 20 to 40% in a complex factory; and a Stanford study finds that robots succeeding at nearly 90% of a task in simulation succeed at just 12% under real conditions. BMW itself puts at 15% the line-efficiency gain where Figure 02 works alongside workers, not in their place. The $25 figure is, moreover, a showcase price, negotiated on a strategic contract, not a settled market rate. Corrected for what the robot actually accomplishes, its cost per unit of work meets the worker’s, or exceeds it.
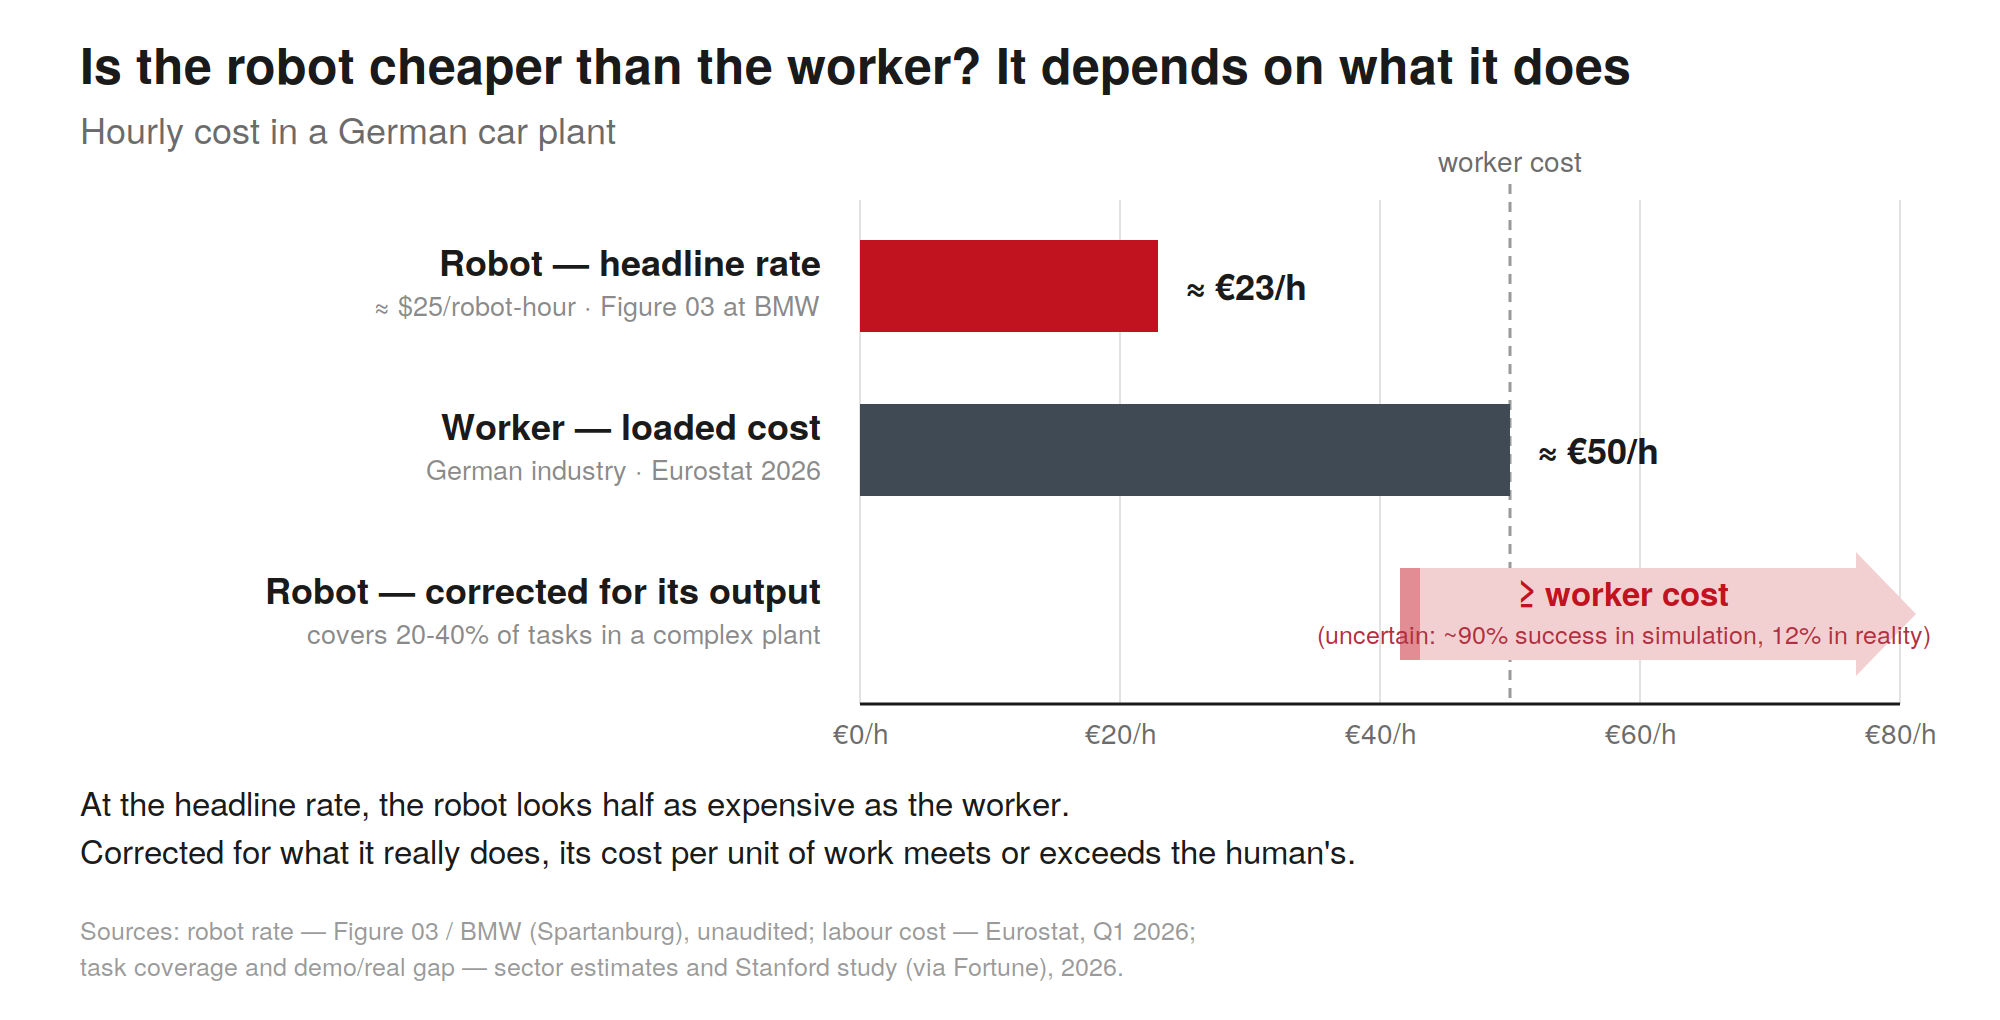
The robot’s advantage lies in what surrounds the gesture. It runs at night, on weekends, across successive shifts, and its purchase price keeps falling. It does not unionise, does not strike, does not take leave. These advantages are of a different order than productivity: they belong to the social relation, and benefit whoever owns the machine.
The factory designed for machines has no human station to replace
The other road draws the workshop around the machines from the drawing board, and the worker does not appear in it. No humanoid: fixed arms, machine vision, software orchestration. This is the model China first tried in electronics. Xiaomi’s Changping plant in Beijing, opened in 2024, produces up to ten million smartphones a year, run end to end by an in-house system, with no staff on the line and no lights. Xiaomi advertises one phone per second; set against the announced volume, the real rate is closer to one every three seconds.
The same principle has reached the car. In Ningbo, the “intelligent” plant of Zeekr, Geely’s premium brand, lines up more than 800 robots in its welding shop alone and produces about 800 electric cars a day, close to 300,000 a year, on a site designed as one piece in three years. Its vice-president claims production “almost entirely” without lights. Almost: the Wall Street Journal notes that the intricate wiring remains manual, and that technicians still come in to maintain the robots. Xiaomi’s electric-vehicle plant in Beijing posts a 91% automation rate, with some lines such as casting fully robotised.
Here the price of a humanoid is beside the point, since there is no humanoid and no human station facing it. The right measure is the whole line against the whole line: capital tied up, throughput, scrap rate, output per square metre. Two gestures are no longer compared; two processes are.
The West automates its old world with the new world’s tool
The decisive gap lies between the two roads. The West modernises what exists because it drags a stock of plants and workforces built for human bodies. Razing and rebuilding China-style would cost capital it will not commit, financial but human too: the accumulated know-how, the employment basins, the social contracts tied around each site. So it slips the humanoid into the old shell. China built its recent lines on new ground, where no workforce had to be displaced on site; it did not spare that human cost, it shifted it into the aggregate. Its manufacturing workforce fell from 115 million in 2013 to under 85 million in 2025, a loss of more than thirty million jobs according to Bloomberg, its exports hitting records over the same span.
The edge comes from the tool. The humanoid carrying out this Western modernisation is, in the main, Chinese. Unitree’s G1 sells for around $16,000 while the Western unit costs six times more; Unitree delivered more than 5,500 robots in 2025, AgiBot about 5,000 per TrendForce, and BYD equips at the latter. The categories are not homogeneous, a full humanoid is not a mobile arm, and these volumes should not be over-read; but the direction is clear. When the West takes the human out of its old workshop, it buys in Hangzhou the machine that replaces them. The product, then the tool, then the data: this is the mechanism this series has named from the start, and Gao Bo occupies its third floor.
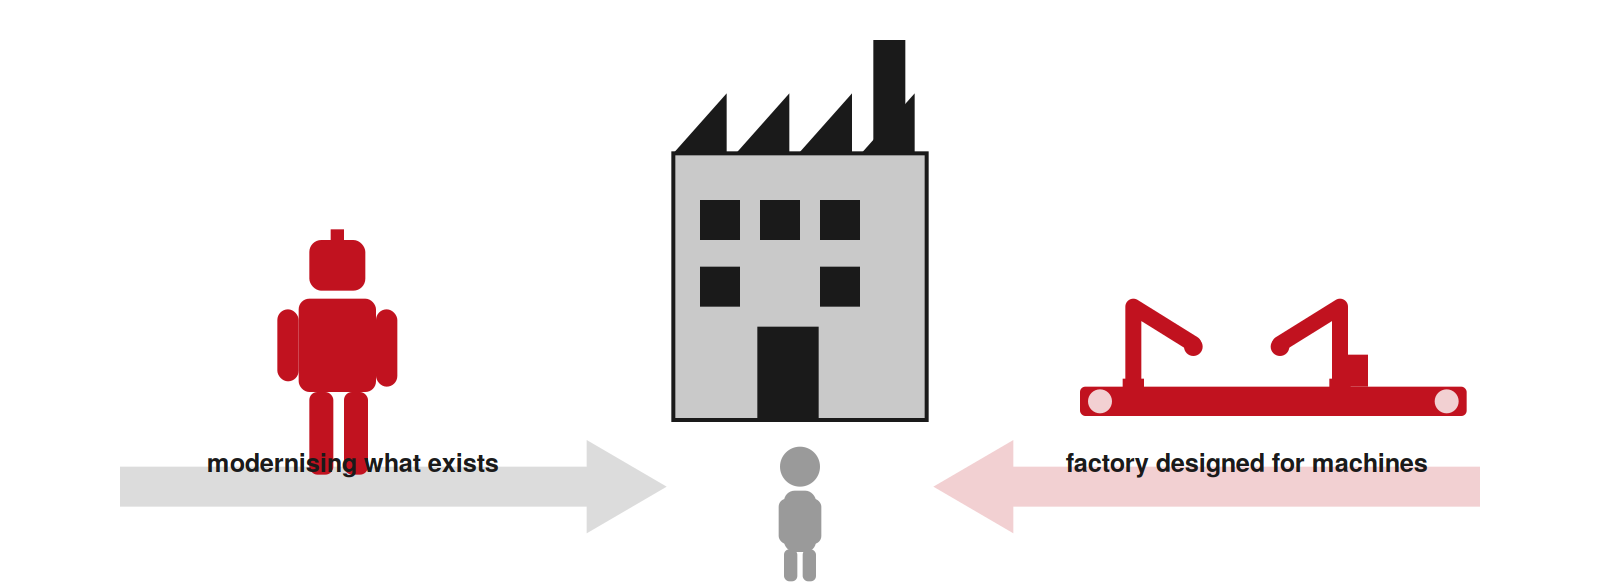
Hyundai crystallises the misunderstanding. We showed in the second part of our Korea dossier that its Atlas project reads as a late replica of the Chinese lights-out model. The map of the two roads makes it precise: it is not even a faithful replica, since the Chinese dark factory employs no humanoids. Hyundai aims at the same result, the lights-out shop, but by the humanoid road and on existing sites, to reach a point China reached by the other path. The whole Western debate over the price of the humanoid, over the hour at which it becomes cheaper than a worker, is held inside the costlier road. It measures with care a contest that is not the one that decides.
The third workshop has neither body nor line
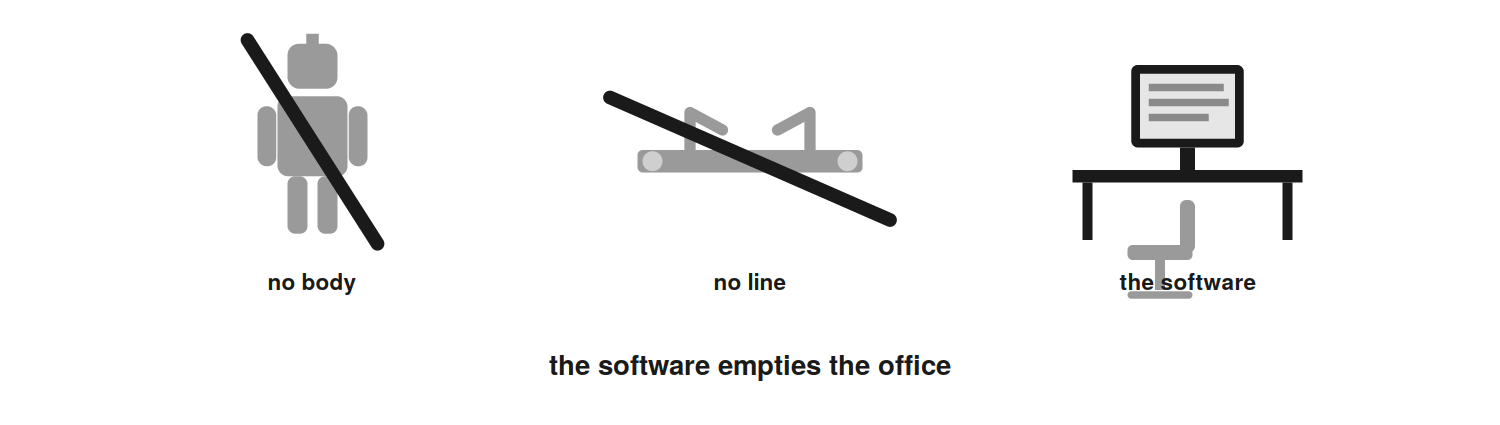
There remains the regime the factory debate forgets, because it resembles no factory. Software empties the office. No body, no physical line: a large language model performs tasks that once occupied white-collar staff. Goldman Sachs boss David Solomon claims an in-house tool now drafts 95% of an IPO prospectus, a document that once mobilised whole teams. Morgan Stanley puts at 200,000 the number of European banking jobs threatened by 2030. McKinsey is cutting its junior-analyst intakes by up to two-thirds. Analysts are not the only ones exposed: coding assistants target IT staff, in banking and beyond, and the threat reaches well past finance.
Caution is in order on this front, for the share of theatre is real: several US banks are freezing hiring more than cutting, and the announced reductions are not all pinned on AI by those who decide them. When a bank explicitly links an attrition-driven headcount fall to its AI tools, the link is established; when it restructures broadly without putting it that way, pinning it on the machine is interpretation, sometimes pretext, AI serving as a handy justification for cuts decided for other reasons. The trend is there nonetheless, and it takes the human out of work by a road that has neither gesture nor chain.
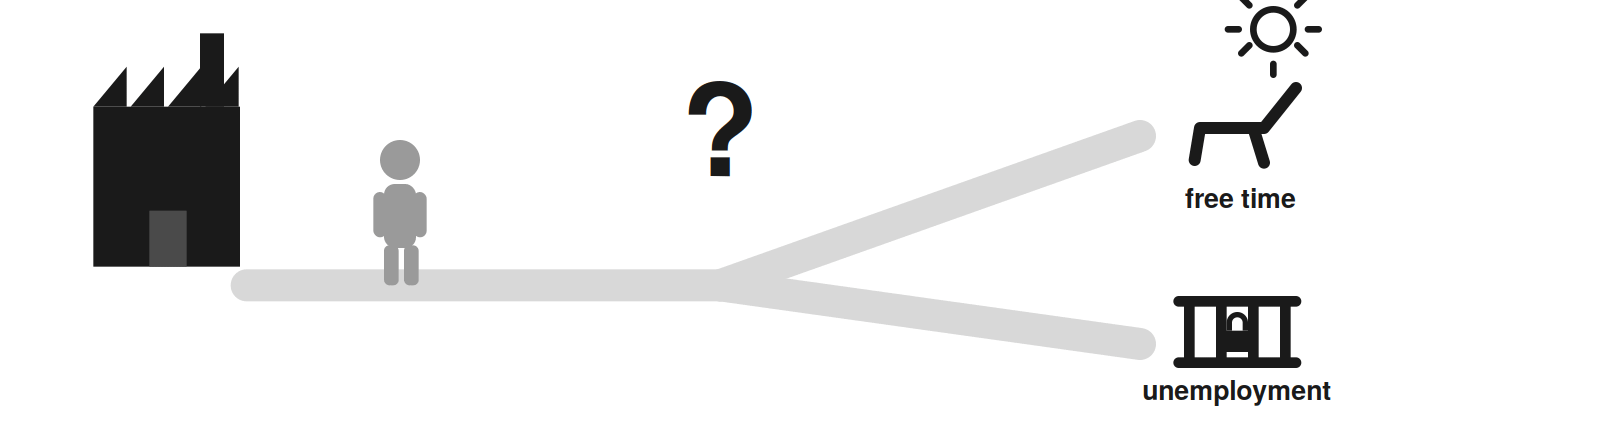
In all three workshops the human leaves; what awaits outside is not decided in the workshop
The three regimes share one result: output held, or raised, with far fewer hours of human work. What the removed hour becomes, free time or unemployment, the machine does not say. It depends on who captures the productivity gain. A gain pocketed through margins and layoffs shrinks purchasing power; a gain shared, as reduced time at maintained income, sustains it. Sharing is therefore not only a matter of justice; it decides whether the system feeds or chokes itself.
Paul Lafargue wrote it a hundred and forty years ago, in The Right to Be Lazy: “our machines with breath of fire” promised leisure and freedom. The machines arrived; leisure did not follow of itself. The promise was not false, it was conditional, and the condition was never technical.
To say the West took the costlier road speaks only of money. Socially, the two roads meet: both take the worker off the shop floor, here by replacing them station by station, there by designing the factory without them. The human cost is measured elsewhere than in the price of the robot, in what society makes of the hours and the people the machine frees.
A reader put to us, in a comment on our Metaplant article, the old under-consumption objection: if automation takes the human out everywhere, who is left to sell to? So far, at each wave — the mechanical loom, the tractor, office software —, demand has reappeared elsewhere, falling costs freeing purchasing power for new activities, with no guarantee it benefits those it displaces, that it returns to the same place, or fast enough. Whether demand holds this time depends on one thing: that the machine’s gains return to those it replaces, as wages and free time, rather than being captured. The question deserves an article of its own, which we may write.
Gao Bo, for her part, trains for three dollars an hour a machine that will work where she herself cannot follow it. The productivity she helps make will belong to someone. The three workshops leave open the only question that counts: to whom.
Main sources: Rest of World (Viola Zhou, 3 June 2026); Bank of America, 2026 humanoid analysis (via Fortune); Goldman Sachs / Deloitte Tech Trends 2026; Stanford research on the simulation/real gap (via Fortune, May 2026); Figure AI and BMW Group releases (2023-2026); Eurostat / Rexecode, labour costs Q1 2026; TrendForce; Bloomberg (Chinese manufacturing employment); trade press on Xiaomi (Changping) and Zeekr (Ningbo), including the Wall Street Journal; Morgan Stanley, McKinsey and Goldman Sachs statements on banking employment; BYD-ization dossier.
All our publications are free and Copyleft. They may be republished, in whole or in part, under following conditions:
→ keeping the title and content
(text, images, editor’s or translator’s notes, boxes)
→ crediting the author(s) and/or translator(s)
→ inserting a clickable link to the source.
Any monetization or commercial use of these publications is prohibited and will be subject to legal action.